
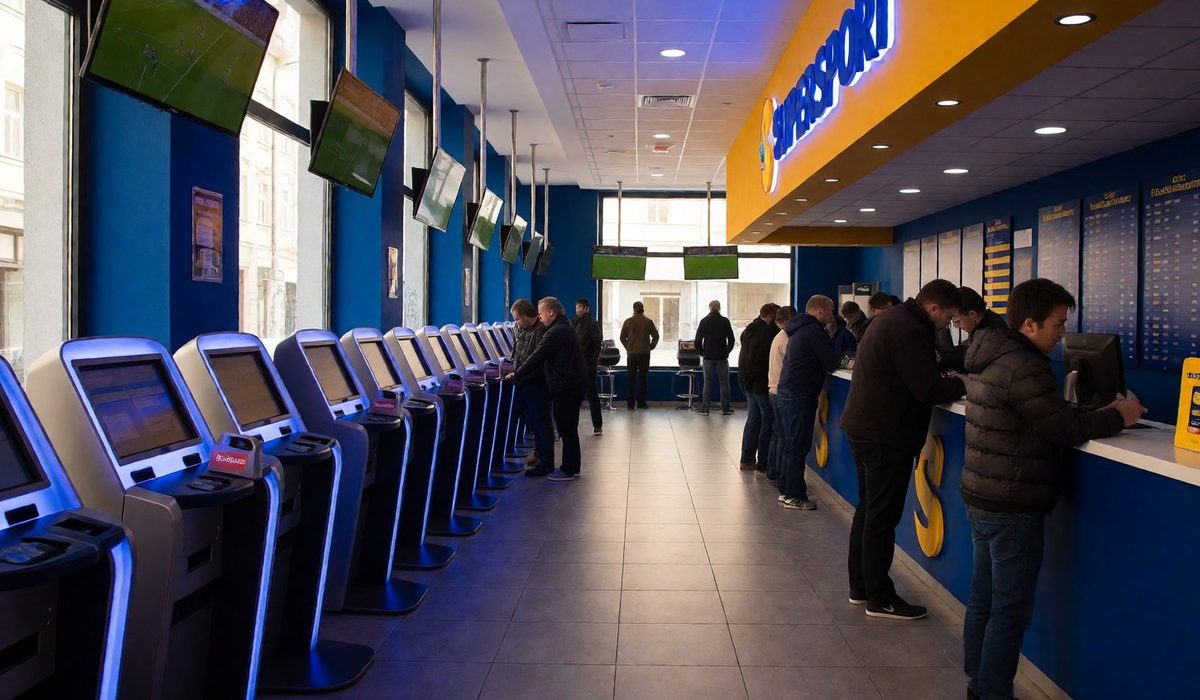
Entain is selling 20% of its Entain CEE unit to EMMA Capital for €425 million, valuing the business at €2.1 billion. This strategic move aims to reduce debt and simplify group structure while managing assets like SuperSport, which holds a 54% market share in Croatia.
Entain’s €425 million deal to sell 20% of Entain CEE to EMMA Capital changes the ownership of the Polish and Croatian assets. This first instalment of a planned exit reduces Entain’s stake from 67.5% to 47.5%. EMMA Capital increases its holding to 42.5%. The Juroszek family foundations keep their 10% but assign voting rights to EMMA. Completion of this deal occurs in Q4 2026. The total cash consideration is approximately €425 million, comprising €395 million payable on completion and an additional payment in early 2027 based on 2026 financial performance. This exit implies an enterprise value of €2.1 billion, which is roughly 10x EBITDA. Entain intends to use the proceeds to reduce debt and expects a £20 million annualised interest saving. I see this as a way to unlock value from a unit that grew its EBITDA by 7% to £183.7 million in 2025. The unit generated £522 million of net gaming revenue in 2025, a 7% increase. This venture began in 2022 when Entain and EMMA partnered to drive expansion across Central and Eastern Europe. This exit is a decisive first step towards Entain fully exiting Entain CEE, according to CEO Stella David.
The Polish market constraints
Poland presents a difficult landscape for STS. The 12% betting tax on turnover, which is unchanged since the 2009 Gambling Act, forces operators to stay disciplined in marketing and product development. While sports betting channelisation reaches 78%, online casino channelisation stays at 61%, and the current state monopoly on online casinos prevents Entain from building a full multi-product sportsbook-plus-casino model in Poland. This lack of casino access traps Entain in a limited market, and I think the dream of a liberalized Polish casino market remains dead. You probably realize that Entain’s UK tax burden exceeds 80% following duty increases. Competition from Betclic and Superbet makes market share harder to hold. Poland’s online revenue grew just 2% in the first half of 2025, while Croatia saw 14% growth. Marek Plota from RM Legal notes that the Polish betting product is strong, but the tax regime compresses margins. The 2017 reform helped build the current market, but it also fixed the high tax environment. The state operator, Totalizator Sportowy, has built its online casino position from zero within just a few years despite strict constraints like an advertising ban.
| Asset / Metric | Value |
|---|---|
| Entain CEE 2025 NGR | £522 million |
| Entain CEE 2025 EBITDA | £183.7 million |
| SuperSport Croatian Market Share | 54% |
| Polish Betting Tax | 12% of turnover |
SuperSport dominance and strategic shifts
SuperSport remains the powerhouse of the CEE unit. The company holds a 54% market share in Croatia. In 2022, Entain paid €690 million for 75% of the business, but in 2023, it paid £750 million for the Polish operator STS. The CEE unit delivered £522 million in net gaming revenue in 2025, which is a 7% increase. The deal structure ensures EMMA gains majority control because the Juroszek family foundations will assign their full voting rights to EMMA once the transaction completes in the final quarter of 2026. This exit reflects a focus on capital allocation rather than holding onto regional local heroes, and Entain’s leadership wants to simplify the group structure to reduce leverage below 3x. Entain’s previous struggles to integrate European acquisitions impacted performance in 2023 and 2024, but the 2022 acquisition included the Croatian company minus5 and the subsidiary Puni Broj. SuperSport’s online focus relies on its proprietary technology solution. Will Entain eventually sell its remaining 47.5% stake?